 For Sale
AED 1,150,000
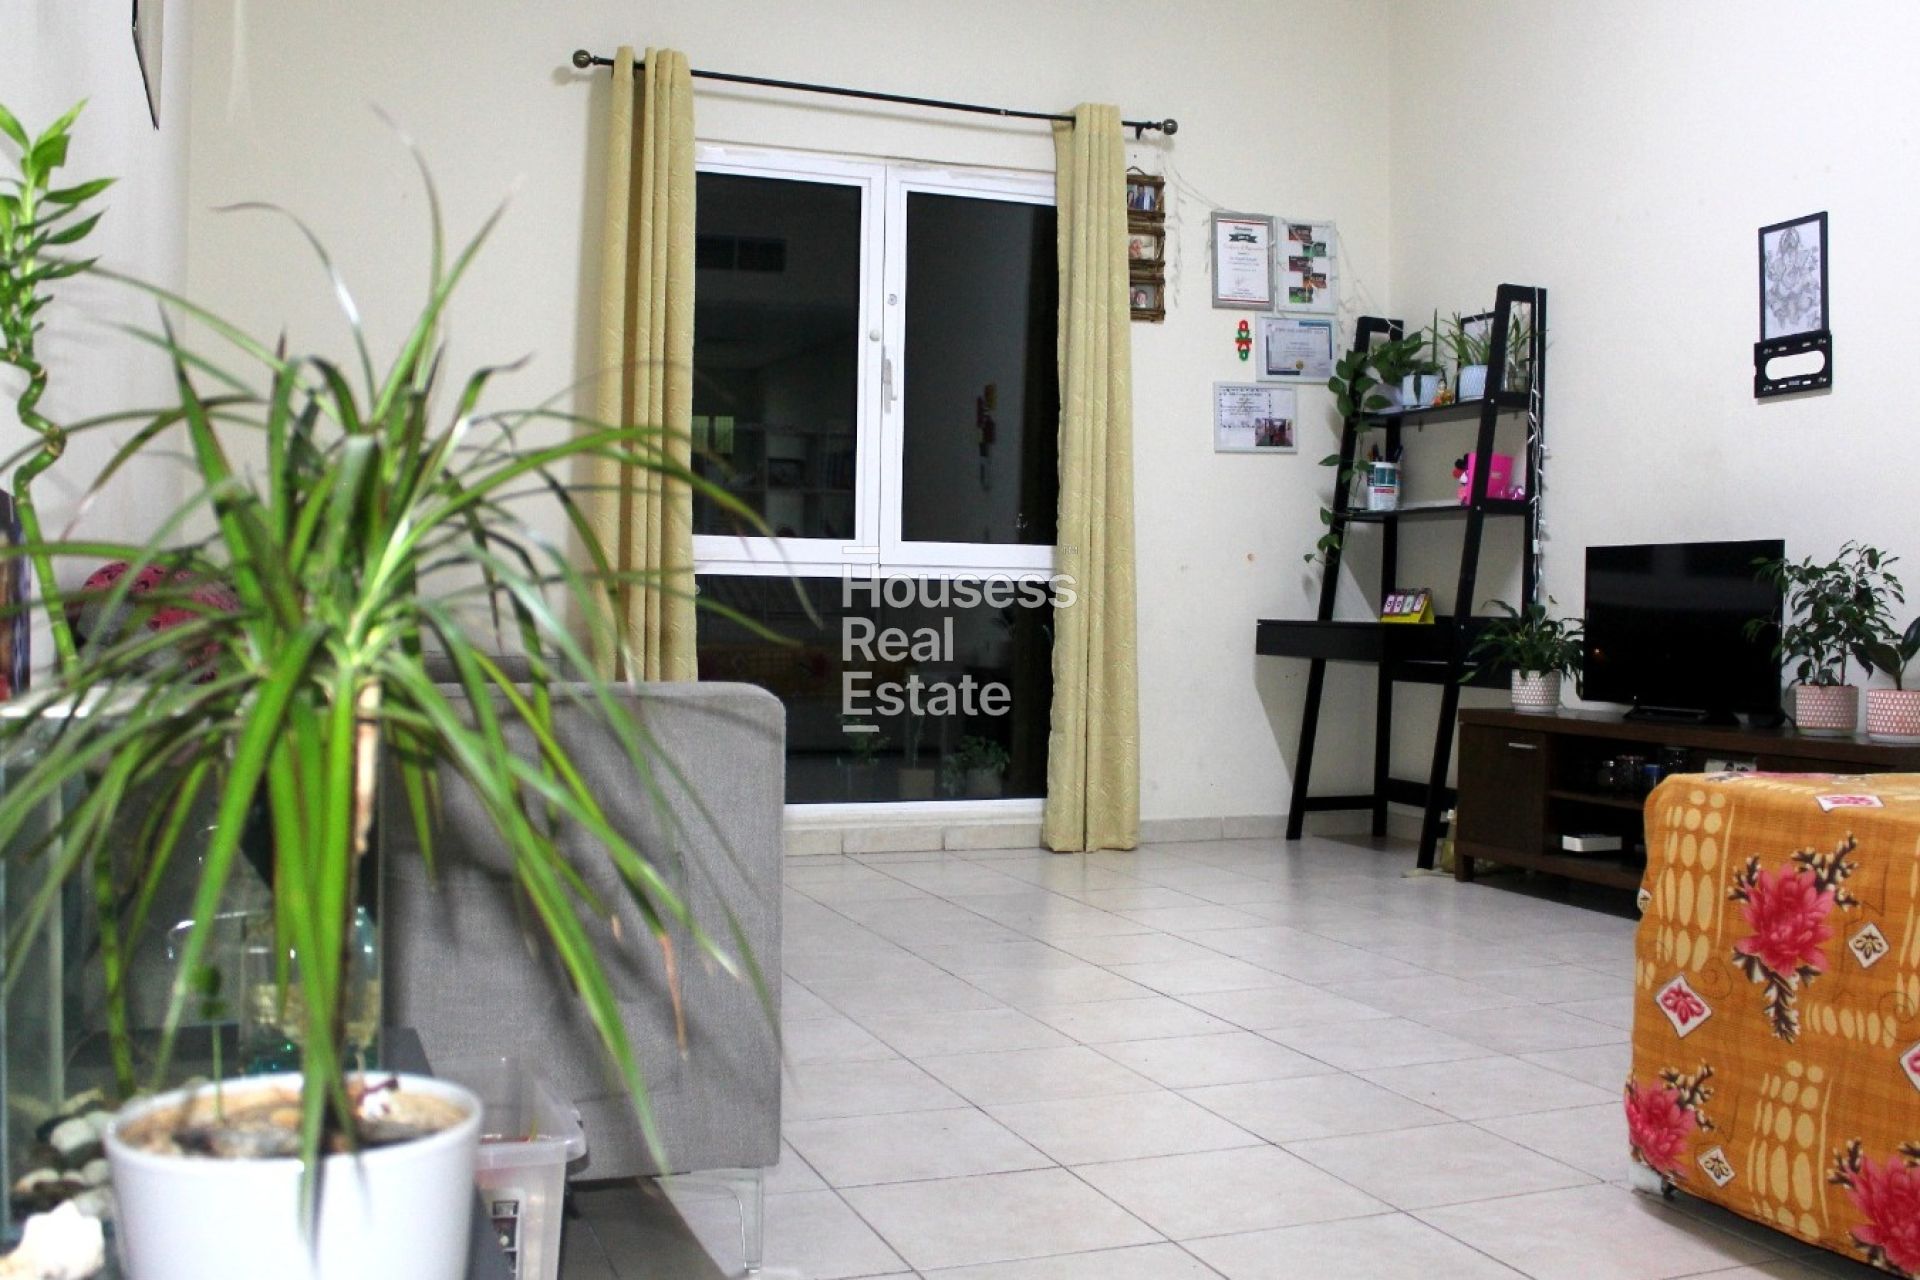
Apartment for Sale Urgent Sale | Private Pool | Below Original Price
Dubai
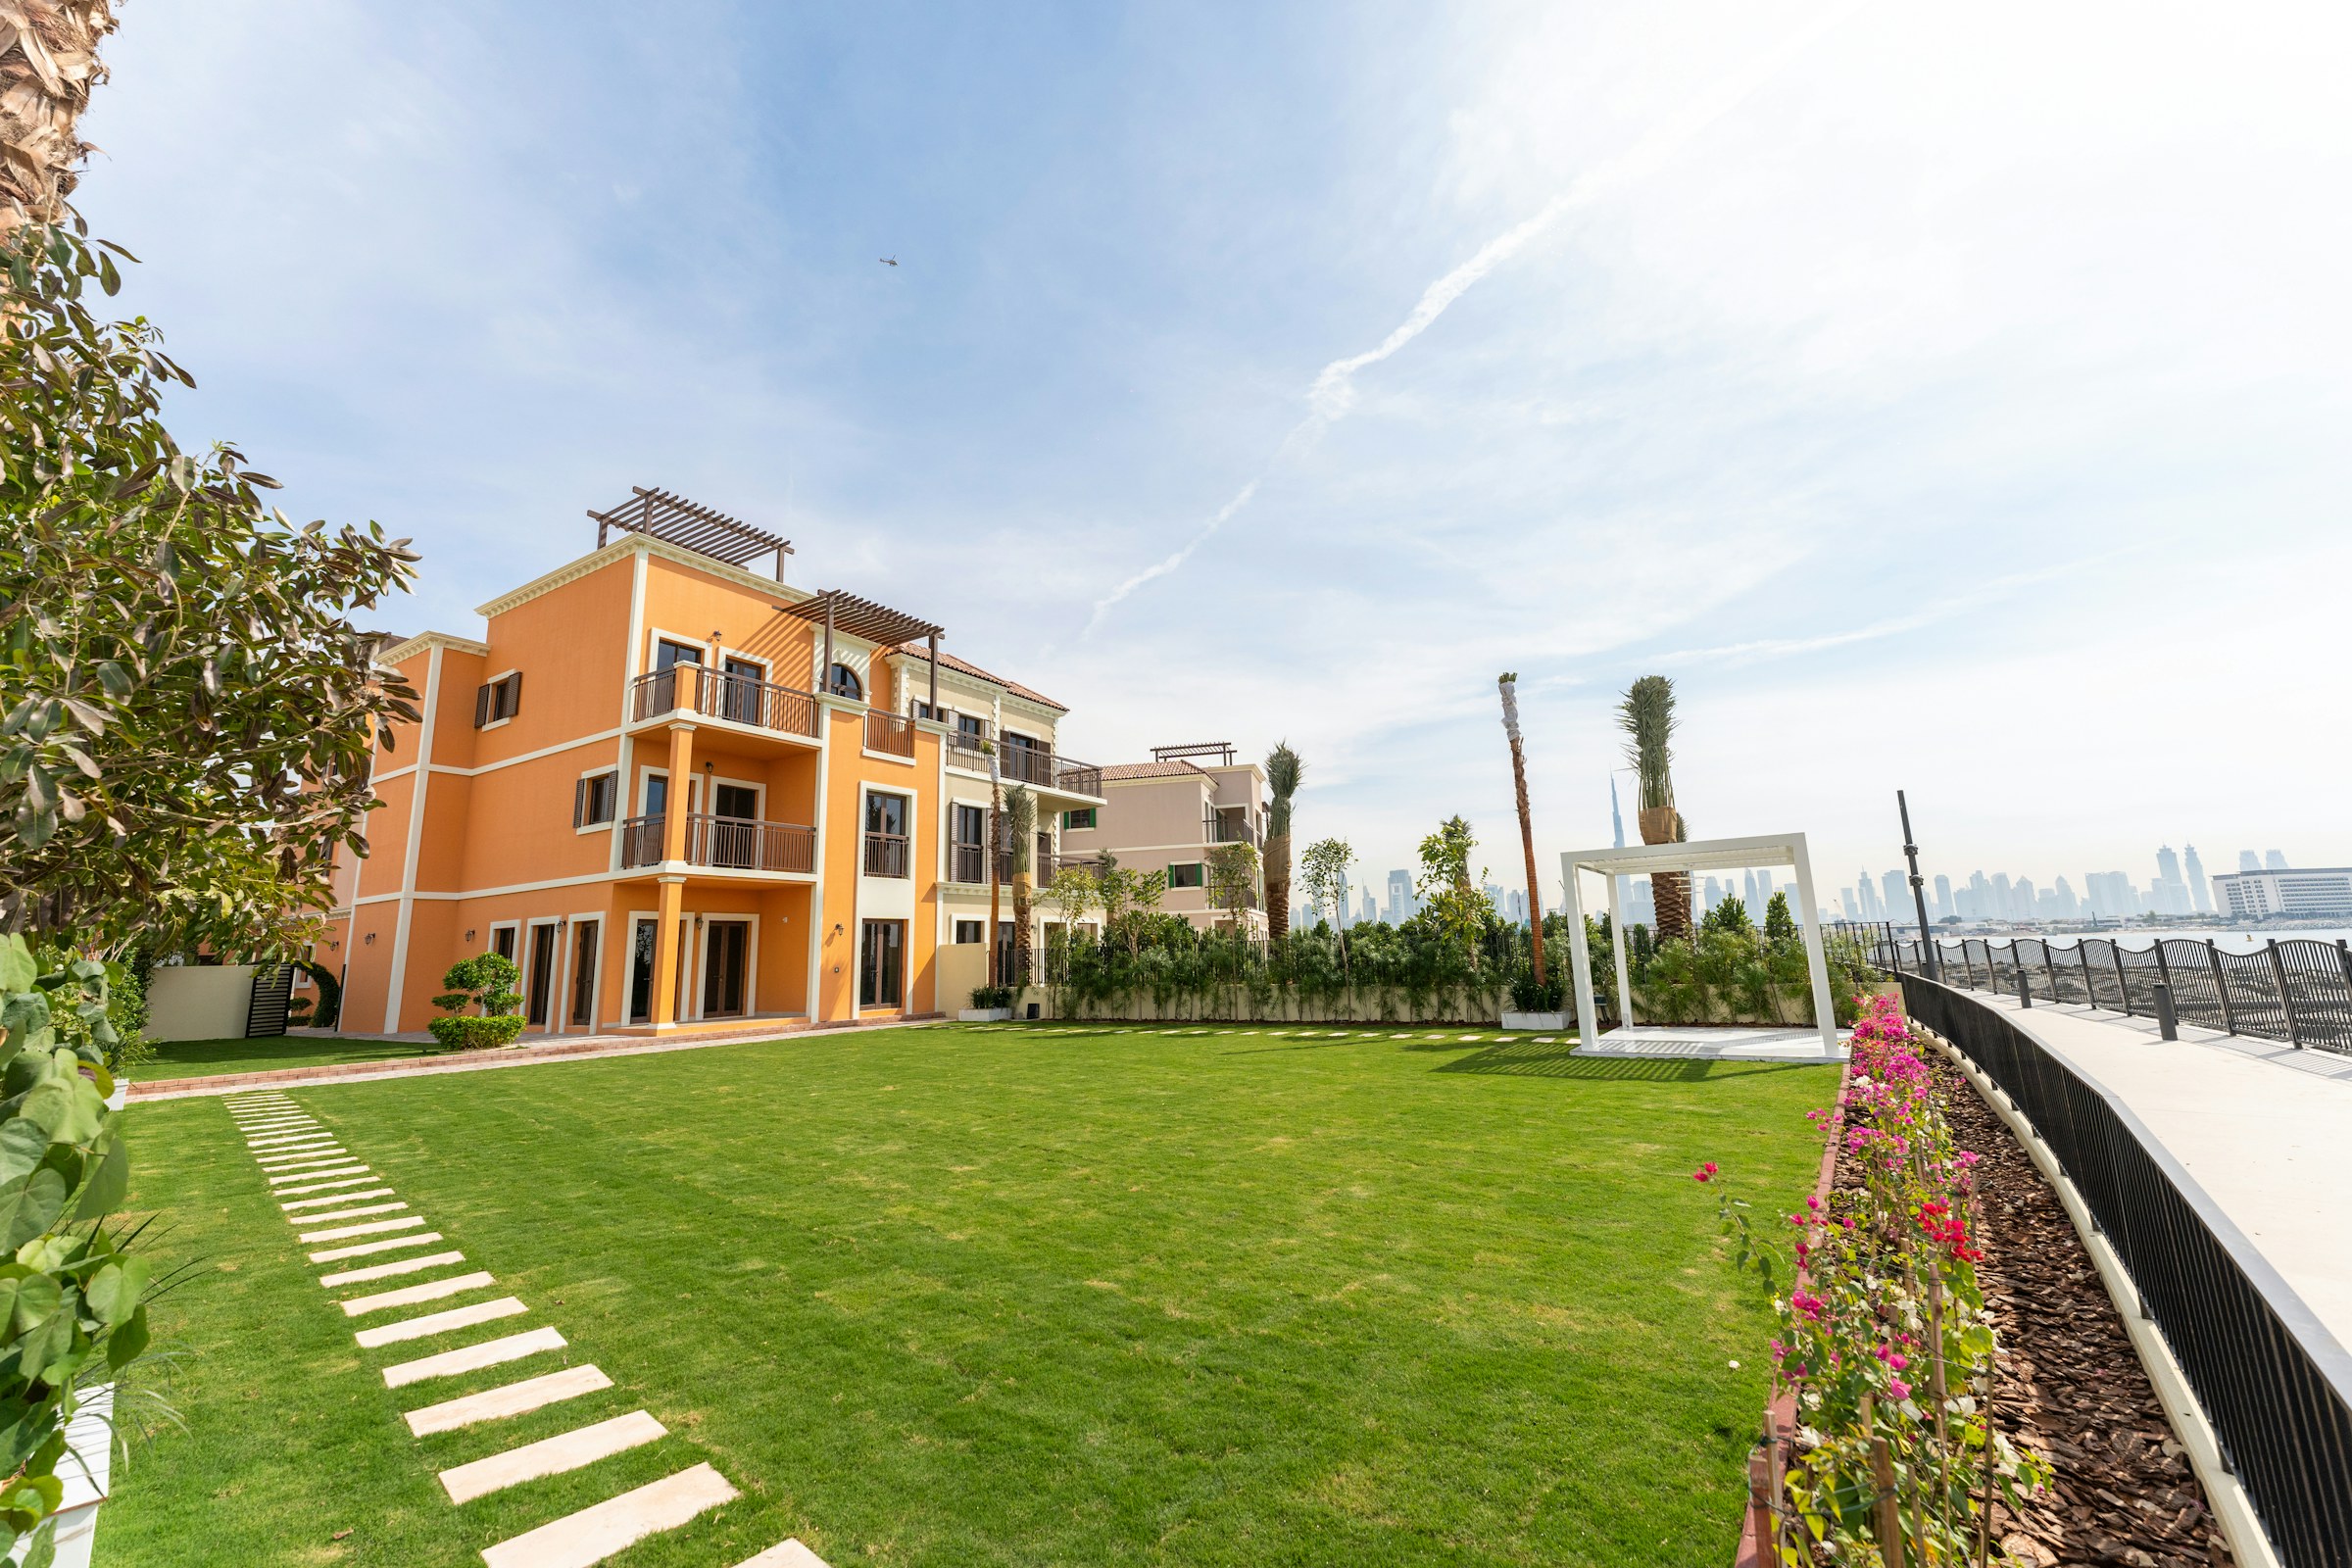
Photo: Ben Koorengevel / Unsplash
Services
Independent advice across the UAE's lenders: what you can borrow, which bank fits your situation, and a pre-approval in hand before you start viewing.
From the first eligibility check to the release of funds at the trustee office.
What you can borrow, based on income, existing commitments, residency and age, before you fall for a property you cannot finance.
Rate, fixed period, what the rate reverts to, early settlement terms and arrangement fees, side by side.
A pre-approval from the lender before viewing, so an offer can be made on the spot and the seller takes it seriously.
The bank valuation booked, the final offer letter checked line by line, and the signing arranged.
Lenders and terms for buyers who live outside the UAE, and what the paperwork looks like from abroad.
Moving an existing mortgage to a better rate, or releasing equity from a property you already own.
Finance for off-plan purchases and for the final payment at handover, where the rules and the lenders differ.
Coordination with the conveyancer so the funds are released on the day of transfer, not the week after.
Find out moreThe UAE Central Bank sets the maximum loan-to-value for residential mortgages, and every bank works within it.
| Buyer and property | Maximum loan | Minimum deposit |
|---|---|---|
| UAE resident, first property, up to AED 5 million | 80% | 20% |
| UAE resident, first property, above AED 5 million | 70% | 30% |
| UAE national, first property, up to AED 5 million | 85% | 15% |
| UAE national, first property, above AED 5 million | 75% | 25% |
| Second or subsequent property | 60% (65% for UAE nationals) | 40% (35%) |
| Off plan, any buyer | 50% | 50% |
Two further limits are set by the Central Bank: the term cannot exceed 25 years, and total monthly debt repayments, including the new mortgage, cannot exceed half of monthly income. On top of that, each bank sets a maximum age at the final instalment, commonly 65 for salaried borrowers and 70 for the self-employed, and banks can and do apply tighter rules than the regulatory ceilings.
Put together, a buyer should plan for roughly 7% to 8% of the purchase price in cash on top of the deposit. We show the full figure before you commit to anything.
Most UAE mortgages offer a fixed rate for an initial period, commonly one to five years, after which the rate reverts to a margin over EIBOR, the interbank rate. The fixed rate is only half the comparison: the reversion margin, the early settlement fee and whether you can overpay are what decide the cost of the loan over its life. We put those side by side rather than leading with the headline rate.
Buying property worth AED 2 million or more qualifies the owner to apply for a ten-year renewable residence visa. Since 2022 the property can be mortgaged, and off-plan purchases from approved developers qualify. If the visa is part of the reason you are buying, tell us at the start, because it affects how the purchase is structured.
A short conversation and a few documents, and you know what you can borrow and what it will cost each month.
The application goes to the lender that fits. A pre-approval is usually valid for 60 to 90 days, long enough to find the property.
Once your offer is accepted, the bank values the property and confirms the loan against it.
Checked line by line for rate, reversion margin, fees and settlement terms before you sign.
The mortgage is signed and registered at the Dubai Land Department on the day of transfer.
Funds released to the seller at the trustee office, coordinated with the conveyancer so nothing waits on anyone.
Most banks look for a monthly income in the region of AED 10,000 to 15,000 for salaried applicants, with higher thresholds for the self-employed and for non-residents. The more useful test is the debt burden ratio: total monthly repayments, including the new loan, cannot exceed half of your income.
At least 20% of the price for a resident buying a first property under AED 5 million, plus the purchase costs, which banks have stopped financing since early 2025. Plan for the deposit plus roughly 7% to 8% of the price in cash.
Yes, from a smaller group of lenders and usually at a lower loan-to-value and a higher rate than a resident would get. The paperwork can be handled from abroad, and we will say early on whether your profile fits.
Typically a few working days once the documents are in, and it is usually valid for 60 to 90 days. If it lapses before you find a property it can be renewed.
Yes, but the maximum loan is 50% of the price for any buyer, fewer banks lend on off plan, and some only release funds at handover. The payment plan and the lender need to be matched from the start.
A fixed rate gives certainty for the initial period; what matters is the rate it reverts to and the cost of leaving early. We compare the whole term, not the introductory figure.
Moving an existing mortgage to another bank for a better rate or to release equity. The new bank settles the old loan; the costs are the early settlement fee on the old mortgage, and the registration and arrangement fees on the new one.
Mortgage brokers in the UAE are usually paid a commission by the lender, so in most cases there is no fee to the borrower. Any fee that does apply is set out in writing before you commit to anything, so you know exactly what, if anything, you pay.
Tell us your income, any existing loans and whether you are resident in the UAE. We will come back with a realistic figure and the monthly cost.
Call +971 4 569 3020
Email info@housess.ae
A pre-approval in hand turns a viewing into an offer the seller takes seriously.